
Get your home insurance claim paid — not denied or lowballed.
A wrongly denied or lowballed claim can leave you paying thousands out of your own pocket. Upload your policy's declarations page for an honest read of what you're actually owed — then the full claim kit helps you claim every dollar of it.
 Claims Assistant · your verdict Example
A real claim, start to finish.
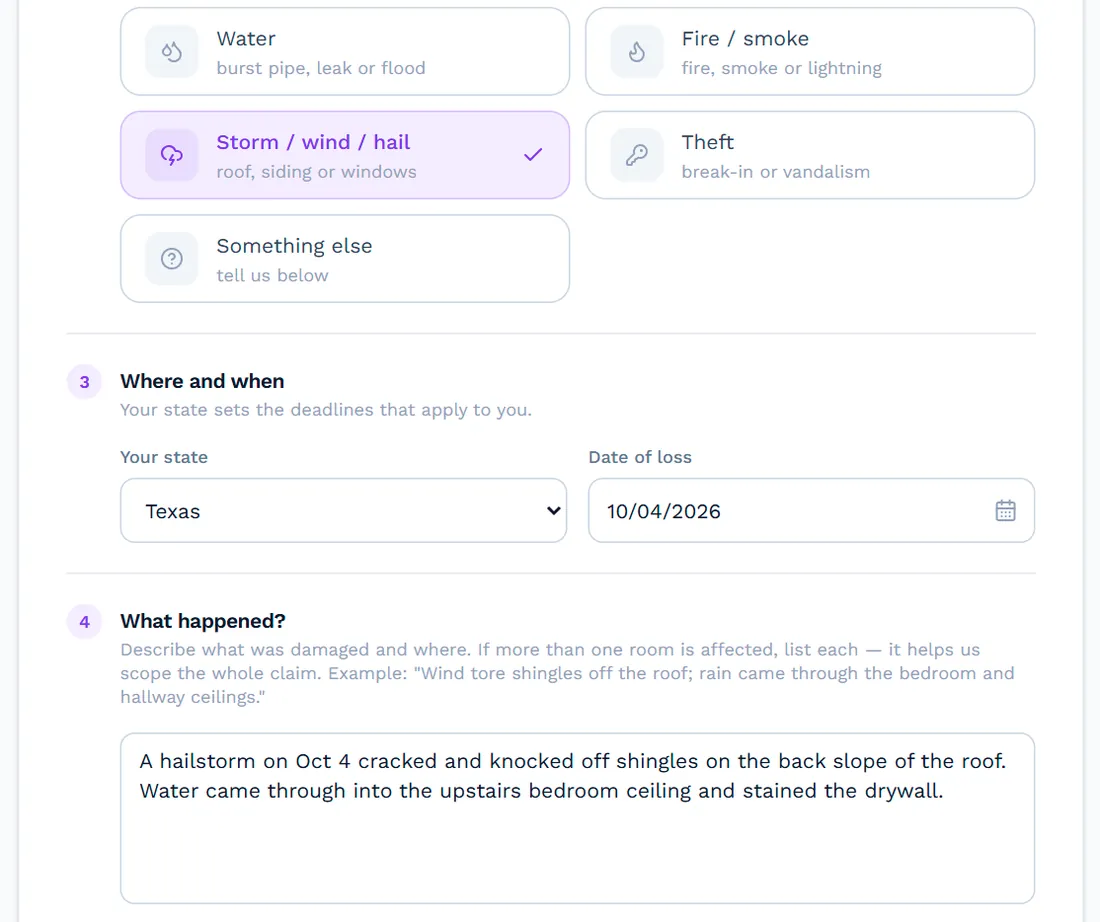
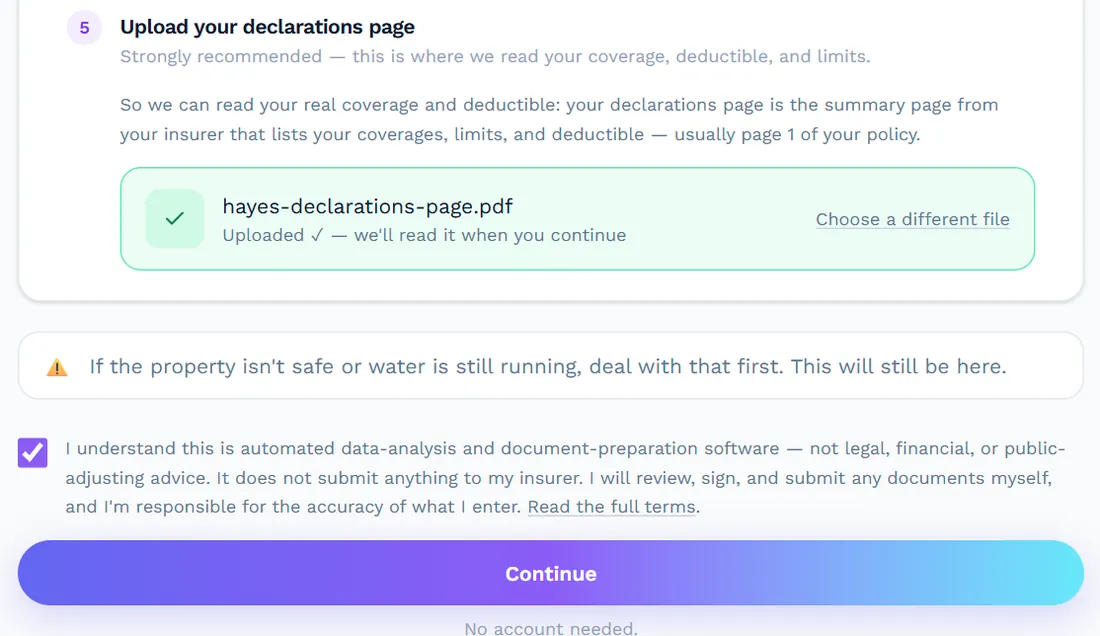
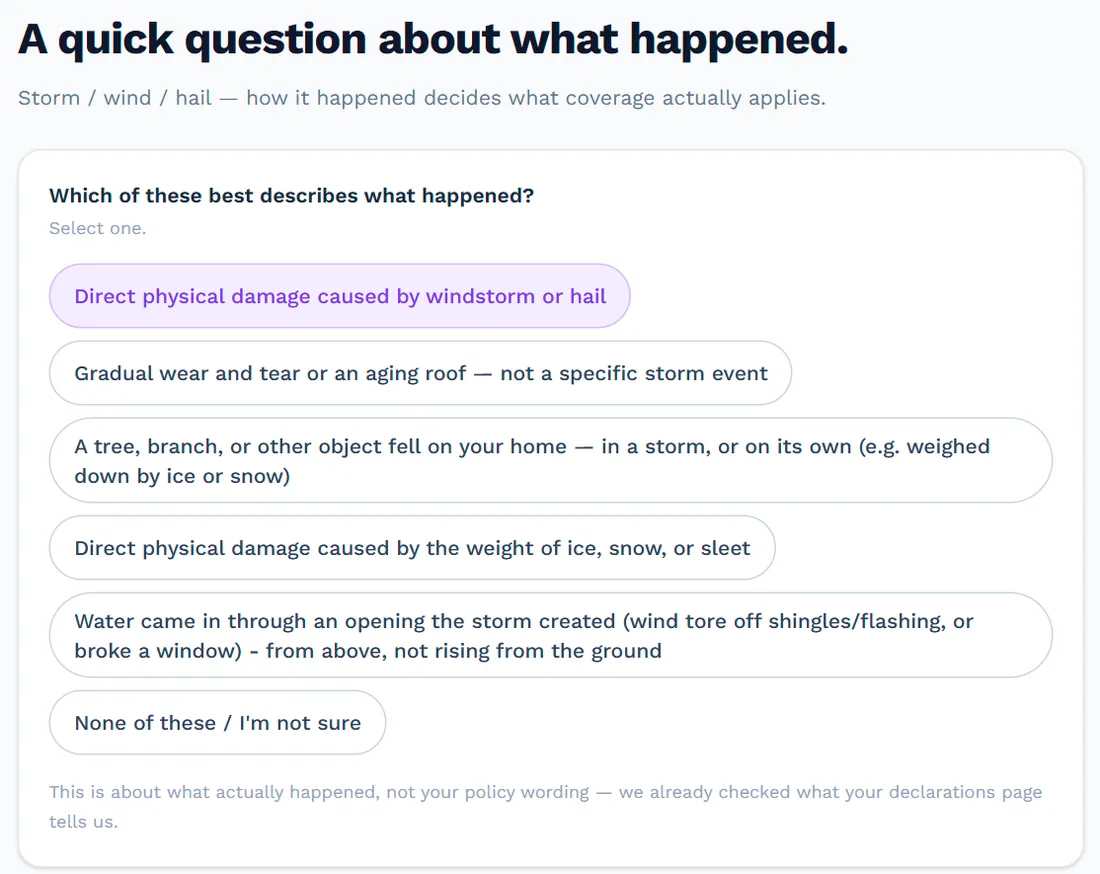
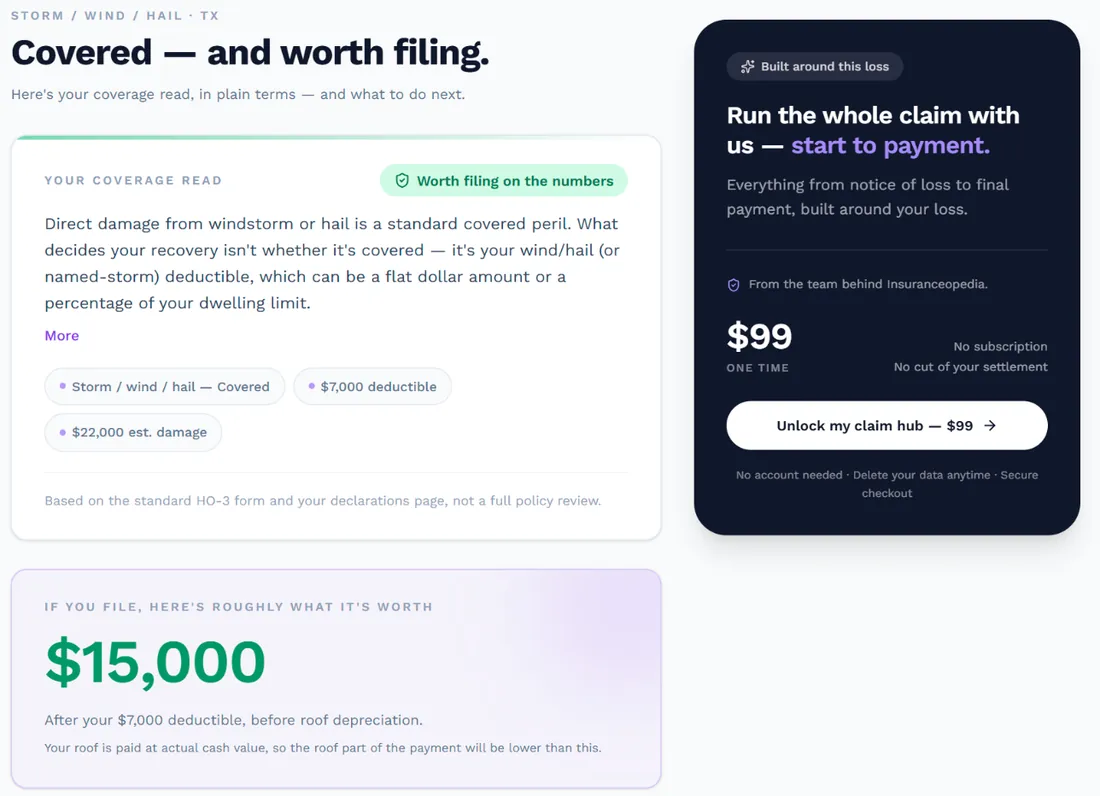
- Your deductible, including any wind/hail deductible
- Your coverage limits
- Endorsements that change what's paid
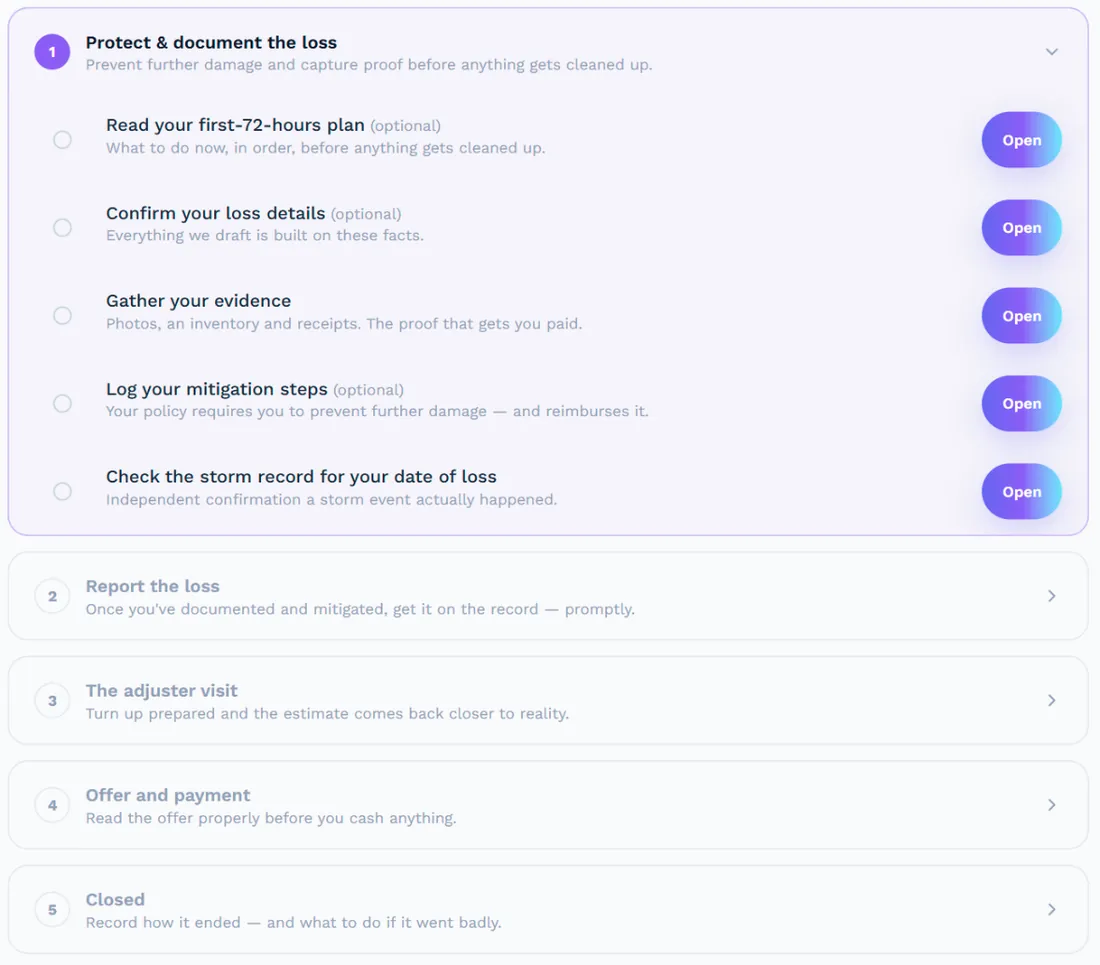
From what happened to the final check — one plan.
- A coverage read before you file
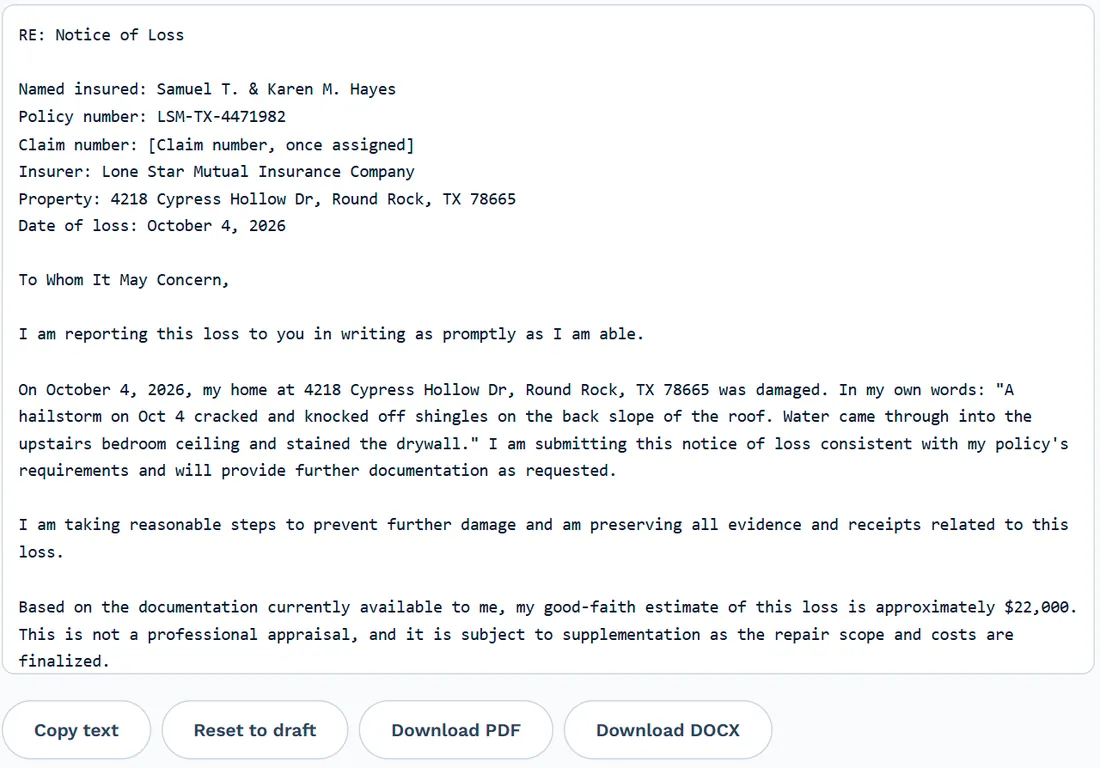
- Letters drafted from your own facts
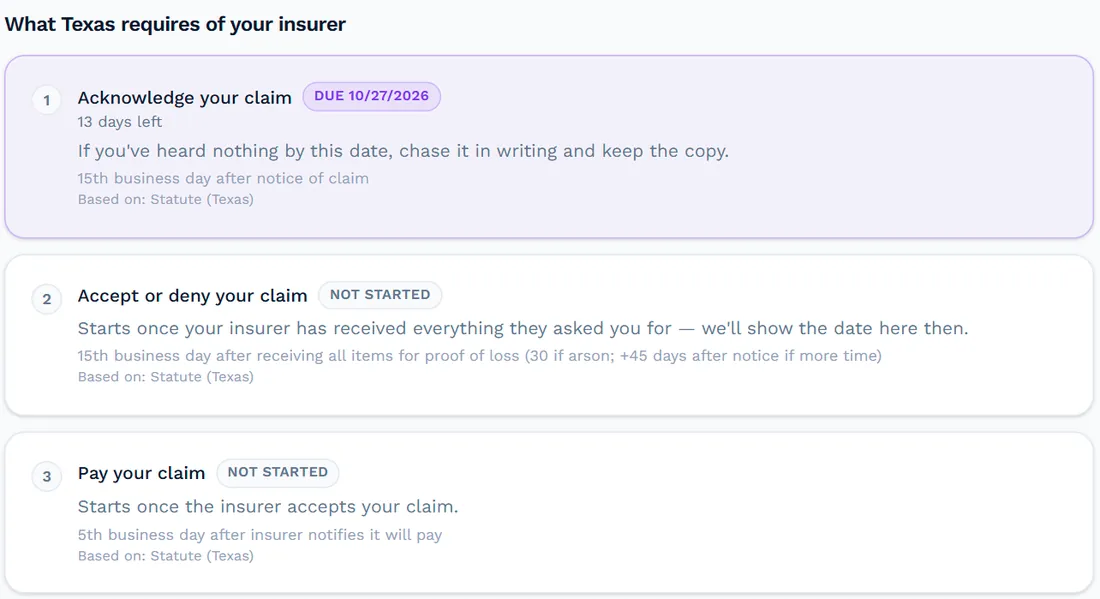
- Every deadline tracked, your insurer's too
- You review and send everything yourself
A claim has clocks most people don't know are running.
Each moment after damage has a window — and once it closes, it's gone. The Assistant walks you through every one.
Capture the evidence
The moment you tidy or start repairs it's gone forever. We tell you exactly what to photograph for your damage type.
Know your coverage
What you say in that first call shapes the claim. Walk in knowing your real coverage and the traps that get claims cut.
Decide if it's worth it
A claim can't be un-filed — it sits on your record ~7 years. We give you the honest math, and say when not to file.
Collect what's owed
Recoverable depreciation and living expenses slip away on deadlines, and low payouts go unchallenged. We track them, audit the estimate, and draft the push-back.
A companion for the whole claim — not just the maths.
You see the read before you pay anything. The full kit — everything below — is $99 flat: no subscription and no cut of your payout.
The honest math first
What you'd actually net after your deductible — and a straight "don't file" when a claim would cost you more than it returns.
Read against your declarations page
Your deductible, limits, sublimits and ACV-vs-RCV — plus the "type traps" adjusters use to cut or deny, spotted before they do.
The paperwork & the proof
A notice-of-loss letter, the exact evidence to capture for your damage type, and a sworn proof of loss if the insurer demands one.
Every deadline & every word
Response and depreciation clocks tracked, a communications log, and the storm record for your date of loss — so nothing lapses or goes unrecorded.
Audit the payout, push back
We check a low settlement for missing scope and withheld depreciation, then draft an appraisal demand, a supplement request, or a regulator complaint.
Straight into the Appeal Assistant
If the claim is denied, everything carries across into a policy-grounded reconsideration built from your denial letter — no starting over.
Handling a claim alone leaves money on the table.
On your own
- ✕ You subtract your deductible from a rough guess — and hope it's worth filing
- ✕ You don't know your own sublimits, endorsements or ACV vs. RCV — so a lowball slips past
- ✕ You might file a claim that raises your premium for almost nothing back
- ✕ Once you file, you're chasing deadlines and the adjuster on your own
The Claims Assistant
- ✓ Tells you what to document now, before the evidence is gone
- ✓ Reads your declarations page — deductible, limits, sublimits, endorsements, ACV vs. RCV
- ✓ Gives an honest should-you-file verdict — including when it isn't worth it
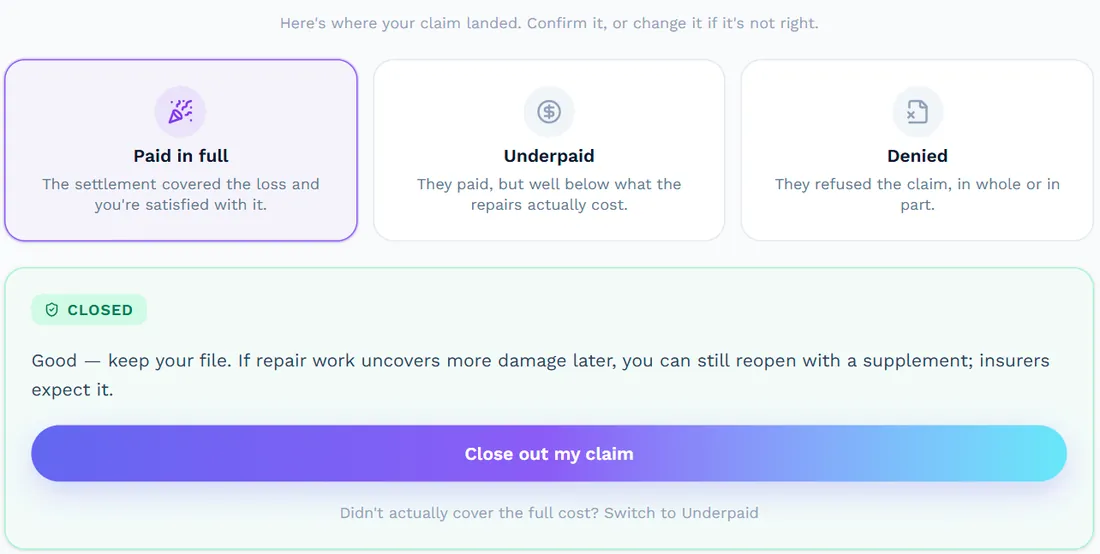
- ✓ Drafts your proof-of-loss and tracks it to payout — audits a low settlement, and builds your appeal if they deny
A denied claim comes out of your own pocket.
If your insurer wrongly denies or underpays, the repair bill is yours. People pay a public adjuster or an attorney a slice of their payout to fight it — the Claims Assistant helps you prepare a strong claim yourself, for $99 flat, with no cut of what you recover.
You see the read before you pay anything. For a large or complex loss a professional may still be worth it, and we'll tell you so.
No catch.
How much does it cost?
You see your read first, with no signup — whether a claim's worth filing and what your policy actually covers. If you go ahead, the full claim kit (the paperwork, deadline tracking, evidence checklist, settlement audit, and push-back letters) is $99 flat per claim. No subscription and no cut of what you recover. A public adjuster typically takes 10–20% of the payout, often $2,000–$4,000 on an average claim.
What happens to my policy if I upload it?
It's read, analyzed, and then discarded — we don't keep the document. If you save and track your claim, we keep only the coverage numbers we read, never the file.
Are you an insurance company or agent?
No. Insuranceopedia isn't an insurer or agent, and we never sell your data — which is exactly why we can tell you honestly when not to file.
Will filing raise my premium?
It can, and repeated claims can affect renewal. We show you that tradeoff plainly before you decide, instead of pushing you to file.
What if they underpay or deny me?
If it's underpaid, we audit the insurer's estimate for missing scope and withheld depreciation and — when there's a genuine basis — draft the push-back: an appraisal demand, a supplement request, or a factual complaint to your state regulator. If it's denied outright, the claim carries straight into our Appeal Assistant for a policy-grounded reconsideration. We'll also tell you honestly when a denial is likely valid.
Is this legal advice?
No — it's clear, sourced information to help you decide. Your policy, your carrier, and your situation are always the final word.
Two minutes now can save you thousands later.
Before you clean up, before you call, before you file — get an honest, policy-specific read. It could save you from paying for a denied claim out of your own pocket.
Check my claim →